Keeping track of business money can seem straightforward at first. A customer pays an invoice, you buy supplies, and your bank balance changes. But after a few weeks, you may have dozens of transactions, several unpaid invoices, and receipts scattered between your email, phone, and desk.
That's when bookkeeping starts to matter.
You don't need to become an accountant to understand your business finances. You need a reliable way to record what happens to your money, keep evidence of each transaction, and check that your records are accurate.
This guide explains how to get started, what to track, and how to build a bookkeeping system that remains manageable as your business grows.
What is bookkeeping?
Bookkeeping is the process of recording and organizing a business's financial transactions.
Whenever your business earns money, pays a bill, purchases equipment, receives a refund, or borrows funds, that activity needs to be recorded appropriately.
Good bookkeeping helps answer practical questions:
How much revenue has the business earned?
What does it cost to operate?
Which customers still owe money?
What bills are coming due?
How much money is actually available?
Are the records complete enough for tax preparation?
Think of bookkeeping as maintaining the financial history of your business. When that history is accurate, you can use it to understand what's happening and make better decisions.
Bookkeeping vs. accounting: what's the difference?
The two terms are related, but they aren't identical.
Bookkeeping focuses on recording and organizing transactions. Accounting uses those records to prepare and interpret financial information, handle reporting requirements, and support business decisions.
For example, a bookkeeper might record $2,000 in sales and $700 in operating expenses. An accountant might analyze those figures alongside other costs, taxes, assets, and liabilities to assess the business's financial performance.
The quality of that analysis depends on the underlying records.
Why bookkeeping matters, even for a very small business
You might be running a side business, freelancing for a few clients, or managing a company with employees. In each case, financial records become more valuable as activity increases.
You can see where your money goes
Without organized records, it's easy to underestimate spending. A few software subscriptions, transaction fees, delivery costs, and small purchases can add up.
Bookkeeping helps reveal those patterns before they become a problem.
You can make decisions using actual numbers
Suppose you want to hire someone, increase your marketing budget, or purchase equipment.
Your bank balance alone doesn't tell you whether the business can comfortably afford it. You also need to consider unpaid bills, upcoming expenses, outstanding customer payments, and other obligations.
Tax preparation becomes easier
Accurate records help you report income and support eligible expense claims. Requirements differ by country and business type, so your records should be organized to meet the rules that apply to you.
You can spot mistakes earlier
Duplicate charges, missing payments, incorrect invoice amounts, and unexpected fees are easier to investigate when transactions are recorded and reviewed regularly.
Step 1: Separate business and personal finances
One of the simplest ways to make bookkeeping easier is to keep business transactions separate from personal spending.
A dedicated business bank account and payment card can help, even where your business structure doesn't legally require them.
Imagine using the same account for groceries, client payments, subscriptions, and business supplies. Every month, you'd need to work out which transactions belong to the business.
Separate accounts reduce that work.
If you occasionally pay a business expense personally, record it correctly rather than ignoring it. Likewise, money you transfer from the business to yourself is not automatically a business expense. Its treatment depends on your business structure and the nature of the transaction.
Step 2: Decide what information to record
A useful bookkeeping system captures enough information to explain each transaction.
For most everyday transactions, start with:
Date: When the transaction occurred.
Description: What the transaction relates to.
Amount: How much was paid or received.
Category: The type of income, expense, asset, or liability.
Payment method: Bank transfer, card, cash, or another method.
Supporting document: An invoice, receipt, contract, or other evidence.
For invoices, you may also need the customer, due date, payment status, and applicable taxes.
For bills, track the supplier, amount owed, and payment deadline.
The objective isn't to collect unnecessary information. It's to make every important transaction understandable and traceable.
Step 3: Organize income and expenses into categories
Categories make your financial records useful.
If you record every payment as simply "money out," you'll know what you spent but not why.
Instead, group transactions according to their purpose.
| Transaction | Possible category |
|---|---|
| Customer pays for a completed project | Service revenue |
| Monthly accounting software subscription | Software expense |
| Office rent | Rent expense |
| Printer paper and stationery | Office supplies |
| Bank account service charge | Bank fees |
| Purchase of a long-lasting business computer | Equipment or fixed asset |
The last example is important: not every purchase is treated as an ordinary operating expense. Some purchases create assets that need different accounting treatment.
Your list of categories is called a chart of accounts. It can start small and become more detailed as your business needs change.
Choose categories that describe your business clearly, and apply them consistently.
Step 4: Understand cash and accrual accounting
Before building your records, it's helpful to understand when income and expenses are recognized.
Cash accounting
Under cash accounting, transactions are generally recognized when money is received or paid.
If you send a $1,000 invoice in March and your customer pays in April, the income is generally recorded when payment arrives.
Accrual accounting
Under accrual accounting, income is generally recognized when earned and expenses when incurred, even if payment happens later.
Using the same example, revenue may be recognized in March, when the work was completed, while the payment received in April reduces the customer's outstanding balance.
Neither approach should be selected solely because it seems easier. Accounting and tax rules vary by jurisdiction and business circumstances. Many businesses must use accrual accounting for reporting purposes, while some qualify for specific cash-basis treatments.
If you're unsure which approach applies, ask a qualified accountant before setting up your books.
Step 5: Understand single-entry and double-entry bookkeeping
These terms describe how transactions are recorded, rather than when they are recognized.
Single-entry bookkeeping is a simpler record of money received and spent. It may be sufficient for some very basic tracking needs, but it has limitations.
Double-entry bookkeeping records the effects of each transaction in at least two accounts. Total debits and credits must balance.
For example, when a business buys $200 of supplies using its bank account, a double-entry system records an increase in supplies expense and a decrease in cash.
You don't have to calculate every debit and credit manually. Accounting software can handle much of the recording behind the scenes.
Double-entry records generally provide a more complete picture when a business has loans, equipment, unpaid bills, or customers who haven't paid yet.
Step 6: Keep receipts, invoices, and supporting documents
A transaction appearing on your bank statement doesn't always explain what you purchased or why it was for business.
Supporting documents fill in that missing information.
Keep records such as:
Sales invoices and payment confirmations
Purchase receipts
Supplier bills
Contracts and agreements
Bank and credit card statements
Refund confirmations
Payroll and tax records, where applicable
Create a consistent way to store them. That might mean digital folders organized by year and month, or a document management system that connects receipts to transactions.
Make sure digital records remain readable, accessible, and backed up.
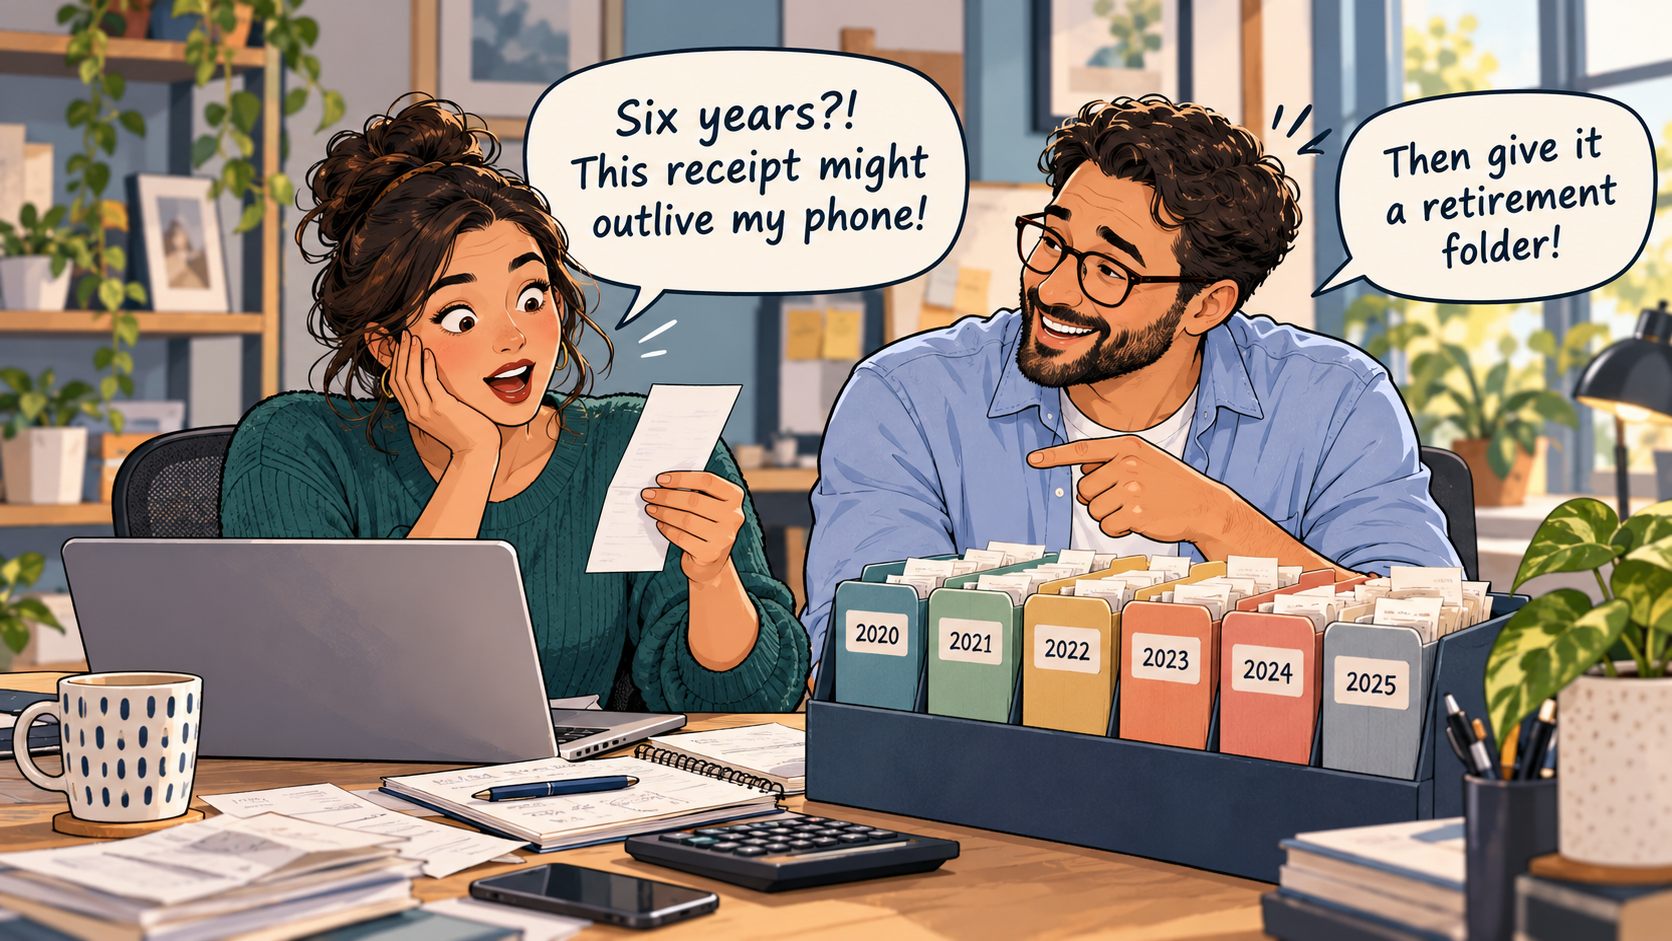
For Canadian businesses: The Canada Revenue Agency generally requires supporting business records to be retained for at least six years from the end of the last tax year to which they relate, with exceptions and special rules. Businesses elsewhere should follow their own jurisdiction's requirements.
Step 7: Reconcile your records
Reconciliation means comparing your bookkeeping records with independent information, such as a bank statement, to identify differences.
Suppose your records show $4,850 in the bank, but your statement shows $4,825.
You investigate and discover a $25 bank fee that hasn't been recorded.
After adding the fee, the figures agree.
Other differences might come from transactions that haven't cleared, duplicate entries, missing deposits, or incorrect amounts.
Reconciliation helps you distinguish normal timing differences from actual errors.
For many small businesses, monthly bank and credit card reconciliation is a sensible starting point. Businesses with high transaction volumes may need to review accounts more frequently.
Step 8: Learn to read three basic financial reports
Bookkeeping becomes much more valuable when you can turn records into useful reports.
Income statement
Also called a profit and loss statement, this report summarizes revenue and expenses over a period.
It helps you understand whether the business is earning more than it spends on the activities reflected in the report.
Balance sheet
A balance sheet shows what a business owns, what it owes, and the owners' equity at a particular date.
Its basic relationship is:
Assets = Liabilities + Equity
Cash flow statement
A cash flow statement explains how cash moves into and out of the business through operating, investing, and financing activities.
These reports answer different questions. A business can show a profit and still struggle to pay its bills if customers haven't paid or cash is tied up elsewhere.
You don't need to master every financial statement immediately. Start by understanding what each one tells you.
A practical bookkeeping example
Consider a freelance designer who starts a month with $3,000 in the business bank account.
During the month:
| Activity | Cash movement |
|---|---|
| Starting bank balance | $3,000 |
| Client payments received | +$2,500 |
| Software subscriptions paid | −$100 |
| Coworking space paid | −$300 |
| Business supplies paid | −$150 |
| Ending bank balance | $4,950 |
The designer also sends a $900 invoice that remains unpaid at month-end.
Here's what matters:
The $4,950 is the ending bank balance, assuming no other transactions.
The $900 unpaid invoice is not cash in the bank. Under accrual accounting, it may be recorded as revenue and accounts receivable, depending on when the work was earned.
The designer also needs to consider any unpaid bills, taxes, loan obligations, and other financial commitments.
This is why accurate bookkeeping involves more than checking the amount in your account.
How often should you do your bookkeeping?
You don't need to spend hours on it every day. The best schedule is one you can follow consistently.
A manageable approach might look like this:
Throughout the week: Capture receipts, record invoices and bills, and make sure unusual transactions have explanations.
Every week: Review new transactions, categorize them, check overdue invoices, and look ahead at upcoming payments.
Every month: Reconcile bank and card accounts, review financial reports, and investigate missing or unexpected entries.
At tax and year-end reporting periods: Review records, gather supporting documents, and complete any required adjustments with professional help where appropriate.
A regular routine is far easier to maintain than rebuilding months of transactions just before a deadline.
Should you use a spreadsheet or bookkeeping software?
A spreadsheet can be a reasonable starting point when you have very few transactions and straightforward finances.
You can create columns for dates, descriptions, categories, income, expenses, and balances.
However, spreadsheets require careful manual maintenance. They can become difficult to manage when you have multiple accounts, outstanding invoices, taxes, reimbursements, or many transactions.
Bookkeeping software can reduce repetitive work by helping organize transactions, invoices, receipts, and financial information in one place.
Whatever tool you choose, look for the ability to:
Record income and expenses accurately
Keep supporting documents organized
Track unpaid invoices and bills
Reconcile financial accounts
Produce reports you can understand
Export or retrieve your records when needed
The right system is the one that supports accurate records without creating unnecessary work.
Common bookkeeping mistakes to avoid
Mixing personal and business transactions. This makes it harder to identify business activity and prepare reliable reports.
Treating every bank deposit as revenue. A loan, owner contribution, or transfer between accounts isn't automatically sales income.
Assuming every purchase is immediately deductible. Some expenses have restrictions, and some purchases must be treated as assets.
Recording invoices as paid before payment arrives. Keep the invoice's status separate from whether revenue has been recognized.
Forgetting small transactions. Fees, refunds, and subscriptions can affect your records even when the amounts seem insignificant.
Skipping reconciliation. Errors may remain unnoticed for months.
Waiting until tax season. A long backlog increases the risk of missing documents and incorrect entries.
When should you hire a bookkeeper or accountant?
Managing your own books can work well when your transactions are simple and you understand the system you're using.
Professional help becomes more valuable when you have employees, inventory, complex sales taxes, financing arrangements, or multiple revenue streams.
Consider seeking help if you're regularly unsure how to categorize transactions, your accounts don't reconcile, or your financial reports don't make sense.
You can also divide the responsibilities: maintain your day-to-day records yourself and have a professional review them periodically.
Start with a system you can maintain
You don't need perfect financial knowledge to begin bookkeeping.
Start by separating business and personal transactions. Record what comes in and goes out. Keep supporting documents. Categorize transactions consistently. Reconcile your accounts and review the results.
As your business grows, your bookkeeping system can grow with it.
The most important outcome isn't a beautifully organized spreadsheet or a sophisticated accounting dashboard. It's being able to understand your business finances, trust your records, and make decisions with confidence.